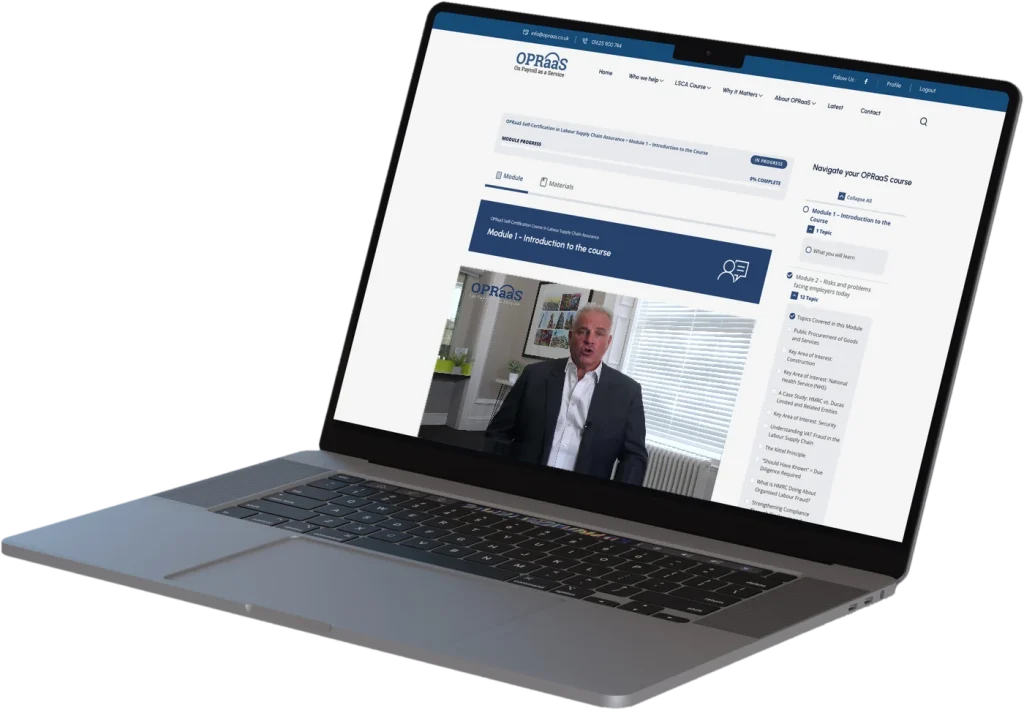
INCLUDED WITH THE OPRaaS VCD AUDIT PLATFORM
Twelve bite-size modules that train anyone in your organisation to audit your labour supply chain and self-certify compliance. Built for recruitment agencies, end-hirers, umbrellas and MSPs.
✓ Learn at your own pace.✓ Audit your own supply chain.✓ Self-certify with confidence.
Book a 30 minute demo on Microsoft Teams, arranged to suit you.
OPRaaS are an approved Government Commercial Agency supplier. Find us on the Digital Marketplace.
Frameworks: RM6310 Audit and Assurance Services (Lots 2 and 4), RM6219, RM6237 and G-Cloud 15.
WHAT YOUR TEAM WILL BE ABLE TO DO
The course provides your employees with all the essential compliance knowledge and understanding they need to build the practical labour supply chain assurance audit skills needed to more effectively audit your live labour supply chain.
When your team has completed the course, they’ll be trained to:
Identify every tier behind your workers, from direct suppliers to umbrella and payroll companies, and keep that picture current.
MODULES 3 AND 4
Apply Check, Act, Review due diligence, and recognise mini umbrella, VAT and phoenix fraud patterns.
MODULES 2 AND 4
Compare PAYE and CIS, verify payslips step by step and test contracts against the statutory requirements.
MODULES 7, 8 AND 9
Learn how the Modern Slavery Act, the Criminal Finances Act and UK GDPR apply across the labour supply chain, and what to look for when you audit.
MODULES 5, 6 AND 10
Learn the Joint and Several Liability regime, work through the 13 JSL Readiness questions and prepare a one-page board report.
MODULE 11
Complete the self-certification audit forms for your role and sign them off on the OPRaaS Audit Platform.
MODULE 12
*Training content current as of 20th Nov 2025. This material is for general guidance only and is not legal or tax advice. Some items (e.g., 2026 reforms) remain subject to final legislation/guidance. Case studies may reflect interim court decisions; allegations are not findings unless stated otherwise.
WHO THE COURSE IS FOR
Written for the HR, tax, procurement, recruitment and payroll professionals who choose, manage and pay your suppliers.
Learn to check the umbrella and payroll companies you work with, and show clients how you do it.
Learn what sits beneath each agency on your PSL, and hold every supplier to one standard.
Check your own payroll, payslip and contract practice against what agencies and end-hirers test for.
Apply one assurance standard across many suppliers, with records ready for scrutiny.
Buying for the public sector? See OPRaaS Public Sector VCD Services.
HOW THE COURSE IS DELIVERED
Every module is built to be easy to follow, whether your team prefers to read, watch or listen.
Every topic comes with Listen Along audio, so your team can learn on the move or listen while they read.
OPRaaS founder Chris Dunn introduces the modules on video, in plain English.
Look up any acronym or term, from JSL to umbrella company, in one click.
Topics tick off as you complete them, modules unlock in order and progress saves automatically.
Practical templates, such as audit request emails and record keeping clauses, plus links to the latest regulatory guidance.
Check understanding and track progress as you go.
Each student receives a printable certificate when they complete the course with snapshots of your team’s progress available for your account lead, upon request.
Help is at hand from the OPRaaS team via email.
COURSE CONTENT
From the risks facing employers today to self-certifying on the OPRaaS Audit Platform.
01
Why labour supply chain assurance matters, and who the course is for.
02
Labour fraud patterns, VAT fraud, the Kittel Principle and HMRC’s enforcement tools.
03
The five LSCA pillars and five practical steps, including Know Your Estate.
04
Mapping your supply chain and applying Check, Act, Review due diligence.
05
Signs to look for, section 54 statements and an incident response protocol.
06
The corporate offence and the six principles behind reasonable prevention procedures.
07
PAYE and CIS compared, Key Information Documents and payroll process integrity.
08
A step-by-step verification process for PAYE payslips and CIS remittances.
09
What compliant temporary worker and CIS subcontractor contracts contain.
10
Lawful bases, the principles of data processing and worker rights.
11 NEW
The regime in force since 6 April 2026, the 13 JSL Readiness questions and a one-page board report.
12
Complete your self-assessment and self-certify on the OPRaaS Audit Platform.
Course content is general guidance, not legal or tax advice.
FROM COURSE TO SELF-CERTIFICATION
01
LEARN
Online and in bite-size modules, at a pace that suits your team.
02
AUDIT
Complete the self-certification audit forms for your role on the OPRaaS Audit Platform, each with an instant Compliance Grade.
03
SELF-CERTIFY
Sign and date each completed form, and keep it with your supporting evidence for at least six years.
The course is included with the OPRaaS Virtual Compliance Director Audit Platform. Find out what the platform does →
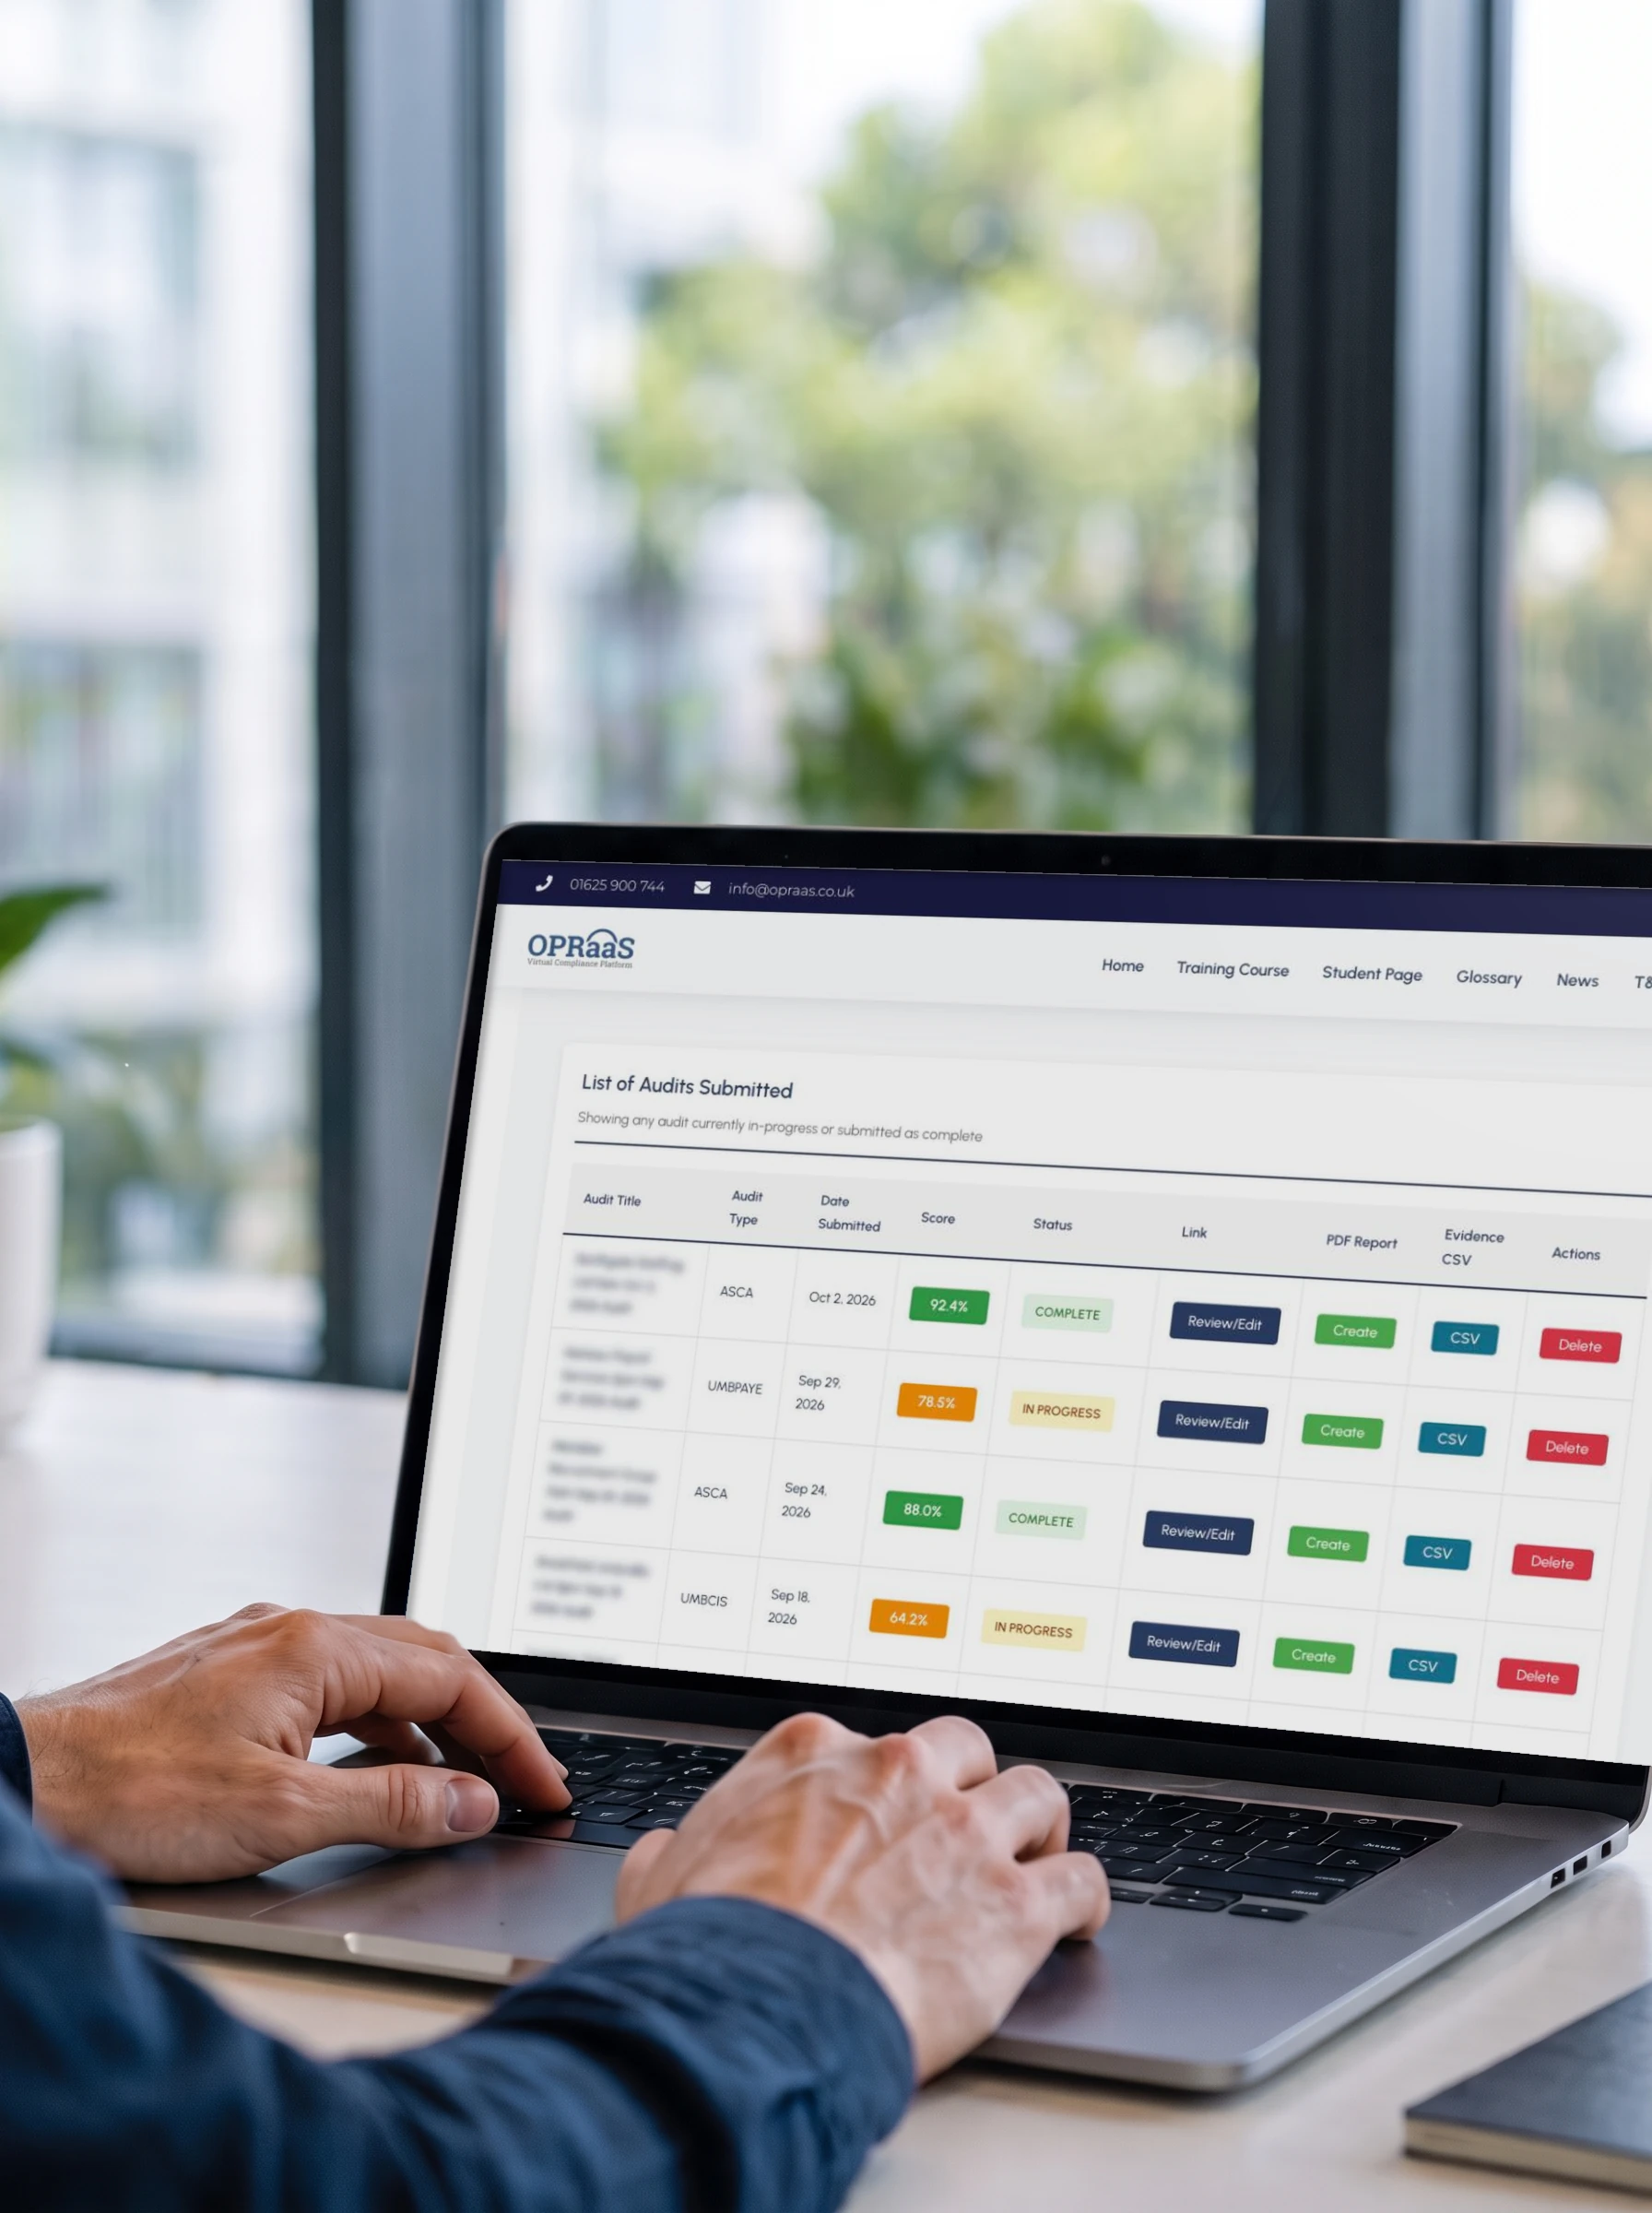
YOUR 30 MINUTE TEAMS DEMO
A guided walkthrough of the course on Microsoft Teams, arranged to suit your schedule.
No preparation needed, and no obligation.
Tell us about your organisation and we will be in touch to arrange a time.
We will not pass your details to anyone else.
PRICING
+VAT per organisation, per year, for the OPRaaS VCD Audit Platform with the LSCA online training course included, and optional 1-to-1 expert support. Your demo includes pricing for your organisation.
OPRaaS Labour Supply Chain Assurance Self-Certification is provided subject to user terms, conditions and an agreement of use. Read the terms and conditions or email info@opraas.co.uk. It does not constitute legal advice, and OPRaaS accepts no liability arising from its use. Subject to service availability.
NEXT STEP
See the course, the videos and the Audit Platform, and get pricing for your organisation.
info@opraas.co.uk · +44 (0)1625 900 744 · opraas.co.uk
Compliance is your asset. Evidenced daily.
LSCA ONLINE TRAINING COURSE
HR, tax, procurement, recruitment and payroll professionals at end-hirers, recruitment agencies, umbrella companies and managed service providers.
Online, in twelve bite-size modules. Modules are introduced on video by Chris Dunn, topics come with Listen Along audio, and there is a searchable glossary, templates and resources, interactive quizzes and a Certificate of Completion. Your team can work at its own pace, and progress saves automatically.
Yes. Access to the course is included with the OPRaaS Virtual Compliance Director Audit Platform, where your team completes the self-certification audit forms for your role.
After the course you complete self-certification forms on the OPRaaS Audit Platform, tailored to your role as an end-hirer, agency or umbrella. They cover CIS, PAYE, Modern Slavery and the Criminal Finances Act 2017.
Each form gives an immediate Compliance Grade showing strengths and gaps. The grade is a guidance indicator, not a legal determination or accreditation. When a form is complete you sign and date it digitally.
No. The course and forms certify your own organisation’s labour supply chain assurance practice. They are not an accreditation for the umbrella or payroll companies you use.
Yes. Module 11 covers the regime in force since 6 April 2026, including the 13 JSL Readiness questions across four control families and a one-page board report.
No. The course is general guidance and does not constitute legal or tax advice.
Pricing is on application, plus VAT, per organisation per year, with optional 1-to-1 expert support. Your demo includes pricing for your organisation.
A 30 minute guided walkthrough on Microsoft Teams of the course, the videos and the OPRaaS Audit Platform, focused on your role. No preparation is needed.
Comprehensive definitions for Labour Supply Chain Assurance compliance terminology
| Acronym | Full Term | Definition |
|---|---|---|
| CFA 2017 | Criminal Finances Act 2017 | UK legislation introducing Corporate Criminal Offence (sections 45/46): failure to prevent the facilitation of tax evasion. Requires businesses to implement 'reasonable prevention procedures' (RPP). The only defence is having adequate RPP or showing it was not reasonable to expect such procedures. |
| MSA 2015 | Modern Slavery Act 2015 | UK legislation mandating supply chain transparency and worker safeguarding. Section 54 requires commercial organisations with ≥£36m turnover to publish annual modern slavery statements (board-approved, signed by director, published on website with prominent homepage link). |
| IR35 | Off-Payroll Working Rules | Tax legislation determining whether a contractor should be treated as employed or self-employed for tax purposes. Since April 2021, medium and large private sector clients must determine contractor status and deduct employment taxes if inside IR35. Requires Status Determination Statement (SDS). |
| JSL | Joint & Several Liability | 2026 legislation imposing strict liability on agencies and end-hirers for umbrella company tax debts, even where due diligence checks have been undertaken. Makes supply chain participants jointly responsible for unpaid PAYE taxes. |
| AWR | Agency Workers Regulations 2010 | UK regulations giving agency workers the right to the same basic working and employment conditions as permanent employees after 12 weeks in a qualifying assignment (12-week parity rule). |
| Good Work Plan | Good Work Plan 2020 | UK employment law reforms requiring written 'section 1 statement' of employment particulars to be given to employees and workers on or before day 1 of engagement (effective 6 April 2020). Sets out key terms but is not itself the contract. |
| Construction Act | Housing Grants, Construction and Regeneration Act 1996 | UK legislation governing payment practices in construction contracts. Section 113 renders "pay when paid" clauses ineffective (except where upstream payer is insolvent). Requires clear due dates, final dates for payment, and compliant payment/pay less notices. |
| Pensions Act 2008 | Pensions Act 2008 | UK legislation establishing workplace pension auto-enrolment requirements. Employers must automatically enrol eligible workers into qualifying pension schemes and make minimum contributions. |
| Acronym | Full Term | Definition |
|---|---|---|
| HMRC | HM Revenue & Customs | UK government department responsible for tax collection, payment of tax credits and benefits, and enforcement of tax law. Operates PAYE, CIS, RTI systems and conducts compliance audits. Business Tax Account provides reconciliation data. |
| GLAA | Gangmasters and Labour Abuse Authority | UK government body regulating labour providers in certain sectors (agriculture, horticulture, shellfish gathering, food processing/packaging) and investigating worker exploitation. Operates licensing regime and has criminal investigation powers. Hotline: 0800 432 0804 (03000 718234 out of hours). |
| ICO | Information Commissioner's Office | UK independent authority upholding information rights. Enforces UK GDPR and Data Protection Act 2018. Personal data breaches must be reported to ICO within 72 hours where there's risk to individuals' rights. Provides guidance on lawful bases, DSARs, and data-sharing. |
| CITB | Construction Industry Training Board | Industry body that collects levy from construction employers (payroll ≥£80k in PAYE in last tax year, or ≥£80k net CIS payments) and provides training grants. CITB levy compliance is audited in construction-focused compliance audits. |
| Acronym | Full Term | Definition |
|---|---|---|
| PAYE | Pay As You Earn | HMRC's system for collecting Income Tax and National Insurance Contributions from employees' wages. Employers deduct tax before paying employees, then remit to HMRC. Operates under Real Time Information (RTI) reporting requirements. |
| CIS | Construction Industry Scheme | Tax deduction scheme for payments to subcontractors in construction industry. Contractors must verify subcontractors with HMRC before first payment and make deductions (20% for verified, 30% for unverified) on labour element only (excluding VAT and allowable materials). CIS300 returns due by 19th following tax month. |
| GPS | Gross Payment Status | CIS status allowing subcontractors to be paid without deductions. Must apply to HMRC and meet compliance tests (business test, turnover test, compliance test). Contractors must verify GPS and keep evidence; continue to file CIS300 but make no deduction. |
| CIS300 | CIS Monthly Return | HMRC return submitted by contractors detailing total payments made to each subcontractor and CIS tax deductions applied. Must be filed by the 19th following the tax month (6th–5th). Should reconcile to subcontractor statements and bank payments. |
| CIS340 | CIS340 Guidance | HMRC's official guidance document defining what constitutes 'construction operations' for CIS purposes. Only work qualifying under CIS340 can legitimately be paid through the Construction Industry Scheme. Includes site preparation, construction, alteration, repairs, demolition. |
| RTI | Real Time Information | HMRC system requiring employers to report PAYE information at or before each pay run. Consists of Full Payment Submission (FPS) for regular pay data and Employer Payment Summary (EPS) for adjustments/recoveries. Must reconcile to payslips and Business Tax Account. |
| FPS | Full Payment Submission | RTI submission reporting gross taxable pay, Income Tax, and NICs for each employee on each payday. FPS values must match payslips. Should not be used to mask under-deductions. |
| EPS | Employer Payment Summary | RTI submission used only for adjustments, such as recoveries, statutory payments, employment allowance claims, or apprenticeship levy. Should not be used to mask PAYE under-deductions. |
| Bacs | Bankers' Automated Clearing Services | UK electronic payment system used for direct debits and credits, including salary payments. Net pay on payslip must match Bacs transfer to worker's bank account. Never use "BACS" (incorrect). |
| UTR | Unique Taxpayer Reference | 10-digit number issued by HMRC to identify individuals and businesses for tax purposes. Required for CIS verification and self-assessment tax returns. Note: UTR alone isn't proof of CIS verification; contractor must verify with HMRC before first payment. |
| NIC / NICs | National Insurance Contributions | UK social security tax paid by employees (via PAYE), employers (as on-costs), and the self-employed (Class 2/4 via self-assessment). Funds state benefits including state pension, statutory sick pay, and maternity allowance. CIS deductions are payments on account of Income Tax and Class 4 NICs. |
| NMW | National Minimum Wage | Legal minimum hourly rate employers must pay workers in the UK. Rates vary by age band. Post-deduction pay (after deductions for employer's own use/benefit) must not fall below NMW. Records must be kept for 6 years. |
| NLW | National Living Wage | Higher rate of National Minimum Wage for workers aged 21 and over. Often referred to together as "NMW/NLW". Different from voluntary Real Living Wage calculated by Living Wage Foundation. |
| AE | Auto-Enrolment (Pensions) | Workplace pension scheme where employers must automatically enrol eligible workers (aged 22+ to state pension age, earning ≥£10k annually) into a qualifying pension. Minimum contributions, opt-out rights, and re-enrolment (every 3 years) required. |
| P45 | P45 (Leaving Employment) | HMRC form given to employees when they leave employment, showing pay and tax details for the year to date. New employer uses P45 to operate correct tax code. Emergency codes (e.g., 1257L W1/M1) apply without P45/P6. |
| Acronym | Full Term | Definition |
|---|---|---|
| DRC | Domestic Reverse Charge (VAT) | VAT mechanism for construction services where the customer accounts for VAT instead of the supplier. Applies to most construction services under CIS340. Designed to combat missing trader fraud in construction supply chains. |
| Kittel | Kittel Principle | EU/UK legal principle that a taxpayer who knew or should have known their transaction was connected to VAT fraud may be denied the right to deduct input VAT. Creates due diligence obligations for supply chain participants. |
| DR | Disguised Remuneration | Tax avoidance arrangements designed to pay individuals while avoiding income tax and NICs, often involving loans, offshore entities, or trusts. HMRC actively targets such schemes. Loan charge applies to outstanding loans. |
| Acronym | Full Term | Definition |
|---|---|---|
| SDC | Supervision, Direction or Control | Key factor in determining employment status under agency rules (ITEPA 2003 s44). If a worker is under supervision, direction or control by any person (client, agency, end-hirer) over how they work, PAYE must be operated. SDC alone is not the general CIS status test—apply usual status tests (control, substitution, mutuality). |
| MOO | Mutuality of Obligation | Employment status indicator examining whether the employer is obliged to provide work and the worker is obliged to accept it. Absence of MOO suggests self-employment; presence suggests employment. |
| SDS | Status Determination Statement | Document required under IR35 reforms (April 2021) where medium/large clients must provide written reasons for their determination of a contractor's employment status for tax purposes. Must be given before contract starts or worker begins work. |
| CEST | Check Employment Status for Tax | HMRC's online tool for determining whether a worker should be classified as employed or self-employed for tax purposes. Results are binding on HMRC if information provided is accurate and not relating to highly complex arrangements. |
| PSC | Personal Service Company | Limited company through which a contractor provides their services. Often used by contractors working outside IR35, but subject to IR35 rules if the underlying relationship is one of employment. Requires SDS from medium/large clients. |
| KID | Key Information Document | Plain-English factsheet (not a contract) that agencies must give to workers before they agree to an assignment (Conduct of Employment Agencies and Employment Businesses Regulations 2003). Includes worked pay illustration, deductions, who pays the worker, benefits. Must be updated within 5 working days of any change. |
| ITEPA 2003 | Income Tax (Earnings and Pensions) Act 2003 | UK tax legislation governing employment income. Section 44 contains agency rules requiring PAYE where worker is under SDC. Section 61N–61R cover off-payroll working (IR35) for public sector and (from 2021) medium/large private sector. |
| DBS | Disclosure and Barring Service | UK government service providing criminal record checks for employment purposes (particularly roles working with children or vulnerable adults). Processing DBS data requires DPA 2018 Schedule 1 condition and appropriate policy document. |
| Acronym | Full Term | Definition |
|---|---|---|
| Umbrella | Umbrella Company | Employment intermediary that employs agency workers and contractors. Handles PAYE, pension, and employment administration while the worker performs assignments for end-clients arranged through agencies. Employer NICs/apprenticeship levy must be funded from assignment rate, not charged to workers as deductions. |
| MUC | Mini Umbrella Company | Fraudulent scheme where multiple small umbrella companies are created to exploit employment allowances and avoid tax obligations. Often phoenixing after accumulating tax debt. A significant compliance risk that supply chain audits help detect. |
| Phoenix | Phoenix Company Scheme | Fraudulent practice where a company accumulates tax debts, is dissolved, and re-emerges as a new entity to escape liabilities. A key risk factor in supply chain due diligence. Tolerance of phoenix suppliers by end users enables fraud cycle. |
| Purported | Purported Umbrella Company | Entity presenting itself as a legitimate umbrella company but failing to meet compliance standards, potentially operating tax avoidance schemes or misclassifying workers. |
| Hybrid | Hybrid Payment Model | Pay arrangement combining different payment methods (e.g., PAYE + CIS, or PAYE + PSC). Requires careful status assessment to avoid disguised remuneration or employment status breaches. |
| Acronym | Full Term | Definition |
|---|---|---|
| UK GDPR | UK General Data Protection Regulation | UK data protection law (retained EU law post-Brexit) governing processing of personal data. Requires lawful basis (Art 6), data minimisation, security, transparency (Arts 13-14), and respect for data subject rights. Works alongside Data Protection Act 2018. |
| DPA 2018 | Data Protection Act 2018 | UK legislation supplementing UK GDPR. Schedule 1 sets conditions for processing special category data (health, biometric, union membership) and criminal offence data (e.g., DBS checks). Provides exemptions (crime prevention, tax collection, legal professional privilege). |
| DSAR | Data Subject Access Request | Individual's right under Art 15 UK GDPR to obtain copy of their personal data. Must respond within one month (extendable by 2 months for complex requests). Usually no fee. Must verify identity proportionately. |
| DPO | Data Protection Officer | Required role for public authorities or organisations conducting large-scale systematic monitoring or processing special category data (Art 37). Oversees data protection compliance, advises on DPIAs, and acts as contact point for ICO and data subjects. |
| LIA | Legitimate Interests Assessment | Assessment required when relying on legitimate interests (Art 6(1)(f)) as lawful basis. Three-part test: identify legitimate interest → demonstrate necessity → balancing test (interests vs individual rights). Appropriate for audit/assurance; avoid consent for audits. |
| DPIA | Data Protection Impact Assessment | Required assessment where processing is likely to result in high risk to individuals (Art 35). Must complete for large-scale, systematic monitoring or extensive special category data processing. Documents risks, mitigation measures, and necessity/proportionality. |
| RoPA | Records of Processing Activities | GDPR requirement (Art 30) documenting all personal data processing activities. Must include purposes, lawful bases, data categories, recipients, retention periods, security measures, and international transfers. Must be available to ICO on request. |
| IDTA | International Data Transfer Agreement | UK mechanism for lawfully transferring personal data outside the UK (replacing EU Standard Contractual Clauses post-Brexit). Required unless recipient country has adequacy decision or other derogation applies. Alternative: UK Addendum to EU SCCs. |
| SCCs | Standard Contractual Clauses | EU Commission-approved contract templates for international data transfers. For UK data exports, use UK Addendum to EU SCCs or UK IDTA. |
| Art 28 DPA | Article 28 Data Processing Agreement | Mandatory contract between controller and processor (Art 28 UK GDPR). Must cover: subject matter, duration, data types, processing instructions, confidentiality, security, sub-processors, data subject rights assistance, breach notification, data deletion/return, audit rights. |
| Art 26 | Article 26 (Joint Controllers) | UK GDPR provision for parties who jointly determine purposes and means of processing. Requires arrangement setting out respective responsibilities, data subject rights, and contact points. Different from controller-processor (Art 28) or controller-controller data-sharing. |
| Controller | Data Controller | Organisation that determines the purposes and means of processing personal data. Bears primary GDPR obligations. Agencies, umbrellas, and end-hirers usually act as independent controllers for their own audit/compliance purposes. |
| Acronym | Full Term | Definition |
|---|---|---|
| LSCA | Labour Supply Chain Assurance | Due diligence framework ensuring compliance with tax, employment, and ethical standards throughout the labour supply chain. Covers PAYE/CIS compliance, modern slavery, CFA 2017, worker rights, and IR35. Aims to detect exploitation, fraud, and phoenixism. |
| PSL | Preferred Supplier List | Vetted list of approved suppliers (typically umbrella companies or agencies) that meet compliance standards. Key governance control for managing supply chain risk. Should be reviewed regularly and require re-certification. |
| End-Hirer | End-Hirer / End Client | The organisation where agency or contract workers ultimately perform their work. Under current regulations, medium/large end-hirers have IR35 status determination responsibilities and supply chain due diligence obligations. |
| CCO | Corporate Criminal Offence | CFA 2017 offence: failure to prevent facilitation of tax evasion by an associated person. Three-stage liability: (1) taxpayer evades tax, (2) associated person criminally facilitates it, (3) organisation failed to prevent. Only defence: reasonable prevention procedures (RPP). |
| RPP | Reasonable Prevention Procedures | The only defence to Corporate Criminal Offence under CFA 2017. HMRC's six principles: risk assessment, proportionate procedures, top-level commitment, due diligence, communication (training), monitoring & review. Must be risk-based and documented. |
| SRO | Senior Responsible Owner | Senior person accountable for CFA 2017 compliance, risk assessments, and implementation of reasonable prevention procedures. Provides top-level commitment and board oversight. |
| MSAT | Modern Slavery Assessment Tool | UK Government tool (Home Office/Cabinet Office) for assessing modern slavery risks in supply chains. Free to organisations registered on UK Government Supplier Registration Service. |
| Acronym | Full Term | Definition |
|---|---|---|
| ASCA | Agency Self-Certification Audit | Most comprehensive audit form with 174 questions across 18 sections. Enables recruitment agencies to self-assess compliance with tax, employment, and supply chain obligations including PAYE, CIS, Modern Slavery, CFA 2017. |
| AUCIS | Agency Umbrella CIS Audit | Audit evaluating recruitment agencies' compliance with CIS requirements when engaging umbrella companies, ensuring proper tax treatment and supply chain integrity. |
| AUPAYE | Agency Umbrella PAYE Audit | Audit assessing recruitment agencies' oversight of umbrella companies' PAYE compliance, including tax deductions, National Insurance contributions, and payroll accuracy. |
| EHUCIS | End-Hirer Umbrella CIS Audit | Audit evaluating end-hirers' due diligence when engaging umbrella companies under CIS, ensuring supply chain compliance and proper contractor treatment. |
| EHUPAYE | End-Hirer Umbrella PAYE Audit | Audit assessing end-hirers' oversight of umbrella PAYE arrangements, covering payroll transparency and worker rights compliance. |
| EHSA | End-Hirer Self-Assessment Audit | Audit enabling end-hirers to self-assess their compliance with supply chain, tax, and employment obligations. |
| EHAA | End-Hirer Assurance Audit | Audit providing end-hirers with an independent assessment of their supply chain compliance, risk management, and due diligence practices. |
| UMBCIS | Umbrella CIS Audit | Audit evaluating umbrella companies' compliance with CIS requirements, including proper contractor treatment, tax deductions, and verification processes. |
| UMBPAYE | Umbrella PAYE Audit | Audit assessing umbrella companies' PAYE compliance, payroll integrity, and worker protection standards. Contains 21 sections (Section 1 info-only, Sections 2-20 audit, Section 21 declaration) vs 18 for most other audits. |
| Self-Cert | Self-Certification Audit | Generic term for labour supply chain compliance audits where organisations self-assess against tax, employment, and ethical standards. Provides documented evidence of due diligence for HMRC inspections. |
| Acronym | Full Term | Definition |
|---|---|---|
| Instance | Audit Form Instance | Individual audit submission. Users can create unlimited instances, each stored as WordPress custom post type with responses in wp_opraas_audit_responses table. Assigned to logged-in user via post_author field. |
| Completion | Completion Score | Frontend metric showing percentage of questions answered (any answer counts). Includes ALL sections: Section 1 checkbox, Section 2 (8 fields), Declaration (7 fields), and all audit questions. N/A responses count as answered. |
| Compliance | Compliance Score | Backend metric measuring quality of compliance. Scoring: Yes=5 points, No=0 points, N/A=0 points (excluded from maximum), Don't Know=1 point. EXCLUDES Sections 1, 2, and Declaration entirely. ≥80% = Compliant, 60-79% = Partially Compliant, <60% = Non-Compliant. |
| Evidence | Evidence Files | Supporting documents uploaded to substantiate audit responses. Stored in AWS S3 via WP Offload Media plugin, with Evidence Table providing S3-aware ZIP downloads that temporarily download from cloud before adding to archives. |
| Red Flags | Red Flags | Warning indicators in audit questions identifying practices that may indicate non-compliance, fraud risk (phoenixism, MUCs, disguised remuneration), or regulatory breaches requiring immediate attention and remediation. |