After a contractor insolvency, can councils show who was on site and who paid them?

Six Greenwich council housing sites stopped when their builder ceased trading. The gates are shut. Who holds the record of the people who worked there?
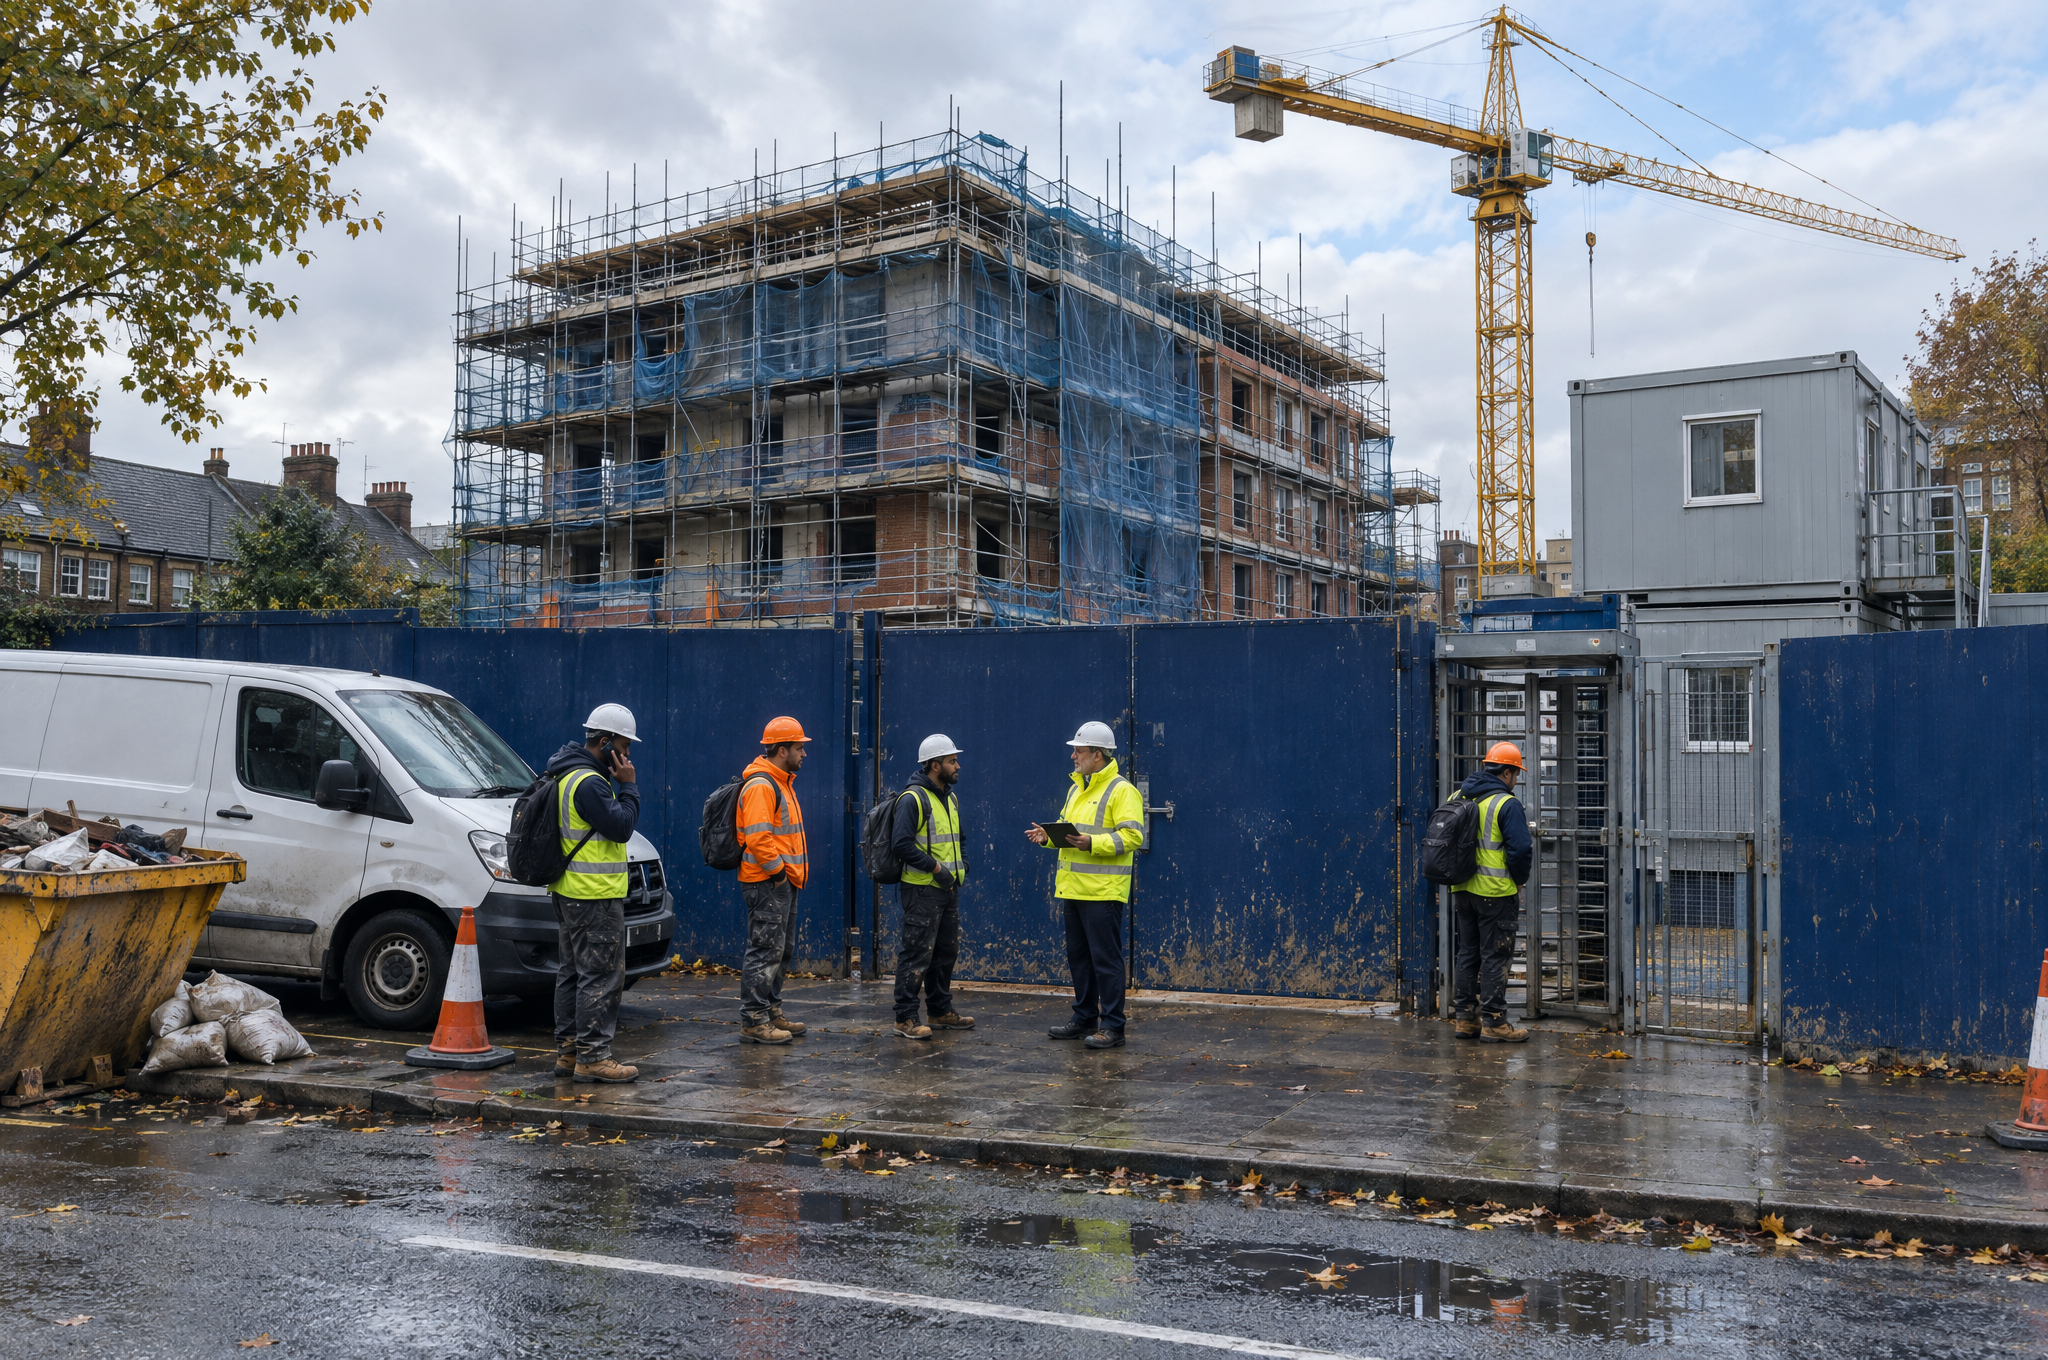
Contractor insolvency leaves construction workers outside a locked site turnstile as a site manager briefs them

Contractor insolvency is more common in construction than in any other industry in England and Wales. According to the Insolvency Service, 3,866 construction companies became insolvent in the 12 months to August 2026, accounting for 17% of cases where the industry was recorded.

The effect is now visible on council housing sites in south-east London.

As Construction News reported on 5 October 2026, six schemes in the Royal Borough of Greenwich’s 1,750-home Greenwich Builds programme have been halted following the collapse of contractor Helix Construct. The council has secured the affected sites and is considering how work on each project can resume.

Securing a site is the immediate task.

Restarting it fairly and with confidence depends on something far less visible: knowing who was working there, which organisation supplied them, who was responsible for paying them and what assurance had already been completed.

That information sits in the labour tiers beneath the main contractor. On the day of a contractor insolvency, it can also be some of the hardest evidence to reconstruct.

What a contractor insolvency leaves behind in the labour supply chain

A main contractor rarely employs the entire workforce delivering a construction project.

Work may be delivered by directly employed staff alongside subcontractors, labour agencies, umbrella companies and self-employed workers operating under the Construction Industry Scheme (CIS).

After a contractor insolvency, those different routes matter because the consequences are not the same.

  • Directly employed staff may be able to claim redundancy pay, holiday pay, unpaid wages and statutory notice pay through the government’s insolvency arrangements, subject to eligibility and statutory limits.
  • Temporary workers supplied by an employment business occupy a different position. Regulation 12 of the Conduct of Employment Agencies and Employment Businesses Regulations 2003 prevents an employment business from withholding payment for work already carried out simply because the hirer has not paid it.
  • Workers employed through umbrella companies introduce another organisation into the payment chain, together with separate PAYE responsibilities.
  • Self-employed CIS subcontractors face a different position again. Amounts owed by an insolvent contractor may become claims against the failed business, while evidence of CIS deductions already made can become particularly important.

Each route creates different records, held by different organisations.

The council commissioning the homes may not routinely hold all of those records itself.

But when delivery stops, the questions quickly travel upstream.

Who was actually working on the project?
Who supplied them?
Who was responsible for paying them?
Were they paid for the work already completed?
And can the client still retrieve the evidence?

Why councils can lose sight of who is building their homes

Public sector buyers normally contract with the main contractor rather than every agency, subcontractor or labour supplier beneath it.

That is a normal feature of construction procurement and an important way of allocating responsibility and commercial risk.

Using several main contractors can also reduce exposure to the failure of any single supplier across a wider programme.

But diversification does not, by itself, provide visibility through the labour supply chain.

That distinction becomes important when a site has to restart after a contractor insolvency.

A replacement or completion contractor may engage some of the same trades, workers, subcontractors or labour suppliers. Without an accessible record from before the failure, establishing who previously worked on the site, how they were engaged and whether outstanding payment issues exist can become a reconstruction exercise.

There is also a wider assurance question.

HMRC’s GfC12 guidance, Help with labour supply chain assurance, encourages organisations to understand the businesses and workforce within their labour supply chains and to assure their integrity on an ongoing basis.

Among the questions HMRC asks businesses to consider are whether they have visibility through the whole supply chain, how they verify that suppliers are assuring the tiers beneath them, and who pays their workforce and how they are paid.

Those are useful questions before a contractor insolvency.

After one, they become considerably harder to answer if the evidence was never maintained.

Contractor insolvency is also a procurement governance issue

The Procurement Act 2023 provides another reason for public sector organisations to understand the financial resilience of organisations involved in delivery.

Under Schedule 7, insolvency involving a supplier or a connected person can constitute a discretionary exclusion ground.

That does not mean every subcontractor, agency or umbrella company beneath a main contractor automatically becomes a “connected person” for the purposes of the Act.

But it reinforces a broader governance principle: public buyers need sufficient visibility to understand the organisations involved in delivering their contracts and where financial distress could affect continuity, compliance or performance.

The issue is therefore larger than conventional credit control.

A supplier can pass financial checks at contract award and encounter difficulties months later.

The useful question is not simply:

Did we check the contractor?

It is:

What has changed since we checked?

Who carries the cost when contractor failure interrupts payment?

For recruitment businesses supplying temporary workers, contractor insolvency creates an immediate cash-flow problem.

Regulation 12 means an employment business cannot simply withhold a worker’s pay for work completed because the hirer has failed to pay the agency.

The employment business can therefore remain responsible for paying its workers while its own unpaid invoices become part of the insolvency process.

Where workers are employed through an umbrella company, there is now an additional tax risk to consider.

The joint and several liability provisions introduced by Finance Act 2026 inserted Chapter 11 into Part 2 of ITEPA 2003. For qualifying umbrella company payments made on or after 6 April 2026, relevant parties can be jointly and severally liable with an umbrella company for PAYE amounts that the umbrella fails to pay.

The precise liable party depends on the structure of the supply chain, but the principle is important: PAYE failure within umbrella arrangements can create financial exposure further up the chain.

That regime is distinct from older PAYE debt transfer powers.

For CIS subcontractors, the evidence question is different again.

Under the Construction Industry Scheme, contractors make deductions from payments to subcontractors and pass those deductions to HMRC. Those deductions are treated as advance payments towards the subcontractor’s tax and National Insurance liabilities.

Payment and deduction statements, together with the contractor’s CIS reporting, therefore form an important part of the evidence trail.

After a contractor insolvency, reconstructing that trail after the event can be considerably harder than maintaining it while the project is live.

Four records you need before a contractor fails

Some contractor insolvencies cannot be avoided.

Losing the labour record can.

For organisations commissioning or managing construction work, four records can make a significant difference when something goes wrong.

1. Who was on site?

Maintain a current workforce record showing the people working on each project, when they worked and their engagement route.

That should make it possible to distinguish between direct employees, agency labour, umbrella-employed workers and CIS subcontractors, and identify the organisation through which each person is engaged.

2. Who paid them?

The workforce record should connect the individual to the legal employer or paying entity.

Appropriate evidence can then be sampled against attendance or timesheet records, including payslips or CIS payment and deduction statements where relevant.

The objective is not simply to know that somebody appeared on a site.

It is to be able to follow the route between work performed, organisation responsible and payment made.

3. What has changed in the supply chain?

Financial and corporate checks should not end when the contract is awarded.

Changes at Companies House, insolvency notices, credit-risk indicators and significant changes in ownership or directors can provide signals that merit further investigation.

Not every change indicates a failing business.

The important point is that material changes prompt review rather than being discovered after the supplier has stopped trading.

4. Can you retrieve the evidence if the supplier disappears?

Contracts and governance processes should establish what labour, right-to-work, payment and supply-chain evidence can be accessed following termination or insolvency.

Otherwise, information that was readily available while a contract was live may have to be negotiated for, recovered from multiple suppliers or reconstructed after an administrator has been appointed.

A halted site can be secured quickly. Restarting it with confidence depends on knowing who was working there, through whom and how they were paid.

How OPRaaS VCD keeps the labour record current

The OPRaaS Virtual Compliance Director (OPRaaS VCD) is designed to maintain that evidence during delivery rather than reconstruct it after a problem occurs.

The platform maps the organisations supplying labour beneath each contract, including agencies, umbrella companies and CIS subcontractors, and records the paying entity associated with each worker.

Right-to-work and identity evidence can be captured through the onboarding and assurance process, while pay evidence and CIS documentation can be sampled against timesheets and workforce records. Where an assurance gap is identified, responsibility for resolving it can be assigned and tracked.

Supplier assurance can also continue throughout the engagement, including monitoring Companies House for director and ownership changes and Creditsafe for credit-risk signals.

If a contractor or labour supplier subsequently fails, the objective is that the workforce record, supplier history and assurance evidence already exist.

The question changes from:

“Can we reconstruct what was happening on this site?”

to:

“Can we produce the evidence?”

That same principle is addressed in Module 3 of the OPRaaS LSCA Self-Certification Course through its Contingent Workforce Tracking topic.

One practical test is simple:

Could your organisation produce a compliant headcount report for its contingent workforce within 24 hours?

For a construction programme, it becomes simpler still:

Can you show who was on this site, who engaged them and who paid them?

OPRaaS is approved on the UK Government Commercial Agency (formerly Crown Commercial Service) frameworks including RM6310 Audit & Assurance Services (Lots 2 & 4), RM6219 Learning & Training Services DPS, RM6237 Learning & Training Services DPS and G-Cloud 15.

What boards and commissioners should test before the next contractor insolvency

Board directors, council commissioners, procurement leaders, main contractors, recruitment agencies and MSPs do not need to wait for an insolvency to discover whether the evidence exists.

Pick one live site.

Ask for a list of the people who worked there last week.

For each person, ask:

  • who engaged them;
  • which organisation pays them;
  • whether they are direct, agency, umbrella or CIS;
  • what right-to-work and identity assurance is held; and
  • what evidence demonstrates that the work recorded and payment made can be reconciled.

Then ask how quickly that information could still be produced if the main contractor stopped trading tomorrow.

If the list takes more than a day to assemble, the gap already exists.

Some contractor failures cannot be avoided.

Losing sight of the labour supply chain when one happens can.

Compliance is your asset. Evidenced daily.

Read next

“Why supplier insolvency is still a live risk across the construction labour supply chain.“

This article draws on the Construction News report published on 5 October 2026, Insolvency Service company insolvency statistics for August 2026, GOV.UK guidance on employer insolvency, the Conduct of Employment Agencies and Employment Businesses Regulations 2003, the Procurement Act 2023, Finance Act 2026, HMRC Construction Industry Scheme guidance and HMRC’s GfC12 Help with labour supply chain assurance.

Talk to OPRaaS about your labour supply chain.

Use the contact form alongside this article or email info@opraas.co.uk.

This article is editorial commentary by OPRaaS Limited (On-Pay-Roll-as-a-Service), drawing on published research, legislation and government guidance. It provides general information and does not constitute legal, tax, employment or compliance advice. Obligations vary according to organisation, contractual arrangements and individual engagements. Appropriate professional advice should be obtained before acting on a specific position.

Share this article

Facebook
X
LinkedIn
LSCA Glossary of Terms

Glossary of Terms

Comprehensive definitions for Labour Supply Chain Assurance compliance terminology

No matching terms found. Try a different search.
Acronym Full Term Definition
CFA 2017 Criminal Finances Act 2017 UK legislation introducing Corporate Criminal Offence (sections 45/46): failure to prevent the facilitation of tax evasion. Requires businesses to implement 'reasonable prevention procedures' (RPP). The only defence is having adequate RPP or showing it was not reasonable to expect such procedures.
MSA 2015 Modern Slavery Act 2015 UK legislation mandating supply chain transparency and worker safeguarding. Section 54 requires commercial organisations with ≥£36m turnover to publish annual modern slavery statements (board-approved, signed by director, published on website with prominent homepage link).
IR35 Off-Payroll Working Rules Tax legislation determining whether a contractor should be treated as employed or self-employed for tax purposes. Since April 2021, medium and large private sector clients must determine contractor status and deduct employment taxes if inside IR35. Requires Status Determination Statement (SDS).
JSL Joint & Several Liability 2026 legislation imposing strict liability on agencies and end-hirers for umbrella company tax debts, even where due diligence checks have been undertaken. Makes supply chain participants jointly responsible for unpaid PAYE taxes.
AWR Agency Workers Regulations 2010 UK regulations giving agency workers the right to the same basic working and employment conditions as permanent employees after 12 weeks in a qualifying assignment (12-week parity rule).
Good Work Plan Good Work Plan 2020 UK employment law reforms requiring written 'section 1 statement' of employment particulars to be given to employees and workers on or before day 1 of engagement (effective 6 April 2020). Sets out key terms but is not itself the contract.
Construction Act Housing Grants, Construction and Regeneration Act 1996 UK legislation governing payment practices in construction contracts. Section 113 renders "pay when paid" clauses ineffective (except where upstream payer is insolvent). Requires clear due dates, final dates for payment, and compliant payment/pay less notices.
Pensions Act 2008 Pensions Act 2008 UK legislation establishing workplace pension auto-enrolment requirements. Employers must automatically enrol eligible workers into qualifying pension schemes and make minimum contributions.
Acronym Full Term Definition
HMRC HM Revenue & Customs UK government department responsible for tax collection, payment of tax credits and benefits, and enforcement of tax law. Operates PAYE, CIS, RTI systems and conducts compliance audits. Business Tax Account provides reconciliation data.
GLAA Gangmasters and Labour Abuse Authority UK government body regulating labour providers in certain sectors (agriculture, horticulture, shellfish gathering, food processing/packaging) and investigating worker exploitation. Operates licensing regime and has criminal investigation powers. Hotline: 0800 432 0804 (03000 718234 out of hours).
ICO Information Commissioner's Office UK independent authority upholding information rights. Enforces UK GDPR and Data Protection Act 2018. Personal data breaches must be reported to ICO within 72 hours where there's risk to individuals' rights. Provides guidance on lawful bases, DSARs, and data-sharing.
CITB Construction Industry Training Board Industry body that collects levy from construction employers (payroll ≥£80k in PAYE in last tax year, or ≥£80k net CIS payments) and provides training grants. CITB levy compliance is audited in construction-focused compliance audits.
Acronym Full Term Definition
PAYE Pay As You Earn HMRC's system for collecting Income Tax and National Insurance Contributions from employees' wages. Employers deduct tax before paying employees, then remit to HMRC. Operates under Real Time Information (RTI) reporting requirements.
CIS Construction Industry Scheme Tax deduction scheme for payments to subcontractors in construction industry. Contractors must verify subcontractors with HMRC before first payment and make deductions (20% for verified, 30% for unverified) on labour element only (excluding VAT and allowable materials). CIS300 returns due by 19th following tax month.
GPS Gross Payment Status CIS status allowing subcontractors to be paid without deductions. Must apply to HMRC and meet compliance tests (business test, turnover test, compliance test). Contractors must verify GPS and keep evidence; continue to file CIS300 but make no deduction.
CIS300 CIS Monthly Return HMRC return submitted by contractors detailing total payments made to each subcontractor and CIS tax deductions applied. Must be filed by the 19th following the tax month (6th–5th). Should reconcile to subcontractor statements and bank payments.
CIS340 CIS340 Guidance HMRC's official guidance document defining what constitutes 'construction operations' for CIS purposes. Only work qualifying under CIS340 can legitimately be paid through the Construction Industry Scheme. Includes site preparation, construction, alteration, repairs, demolition.
RTI Real Time Information HMRC system requiring employers to report PAYE information at or before each pay run. Consists of Full Payment Submission (FPS) for regular pay data and Employer Payment Summary (EPS) for adjustments/recoveries. Must reconcile to payslips and Business Tax Account.
FPS Full Payment Submission RTI submission reporting gross taxable pay, Income Tax, and NICs for each employee on each payday. FPS values must match payslips. Should not be used to mask under-deductions.
EPS Employer Payment Summary RTI submission used only for adjustments, such as recoveries, statutory payments, employment allowance claims, or apprenticeship levy. Should not be used to mask PAYE under-deductions.
Bacs Bankers' Automated Clearing Services UK electronic payment system used for direct debits and credits, including salary payments. Net pay on payslip must match Bacs transfer to worker's bank account. Never use "BACS" (incorrect).
UTR Unique Taxpayer Reference 10-digit number issued by HMRC to identify individuals and businesses for tax purposes. Required for CIS verification and self-assessment tax returns. Note: UTR alone isn't proof of CIS verification; contractor must verify with HMRC before first payment.
NIC / NICs National Insurance Contributions UK social security tax paid by employees (via PAYE), employers (as on-costs), and the self-employed (Class 2/4 via self-assessment). Funds state benefits including state pension, statutory sick pay, and maternity allowance. CIS deductions are payments on account of Income Tax and Class 4 NICs.
NMW National Minimum Wage Legal minimum hourly rate employers must pay workers in the UK. Rates vary by age band. Post-deduction pay (after deductions for employer's own use/benefit) must not fall below NMW. Records must be kept for 6 years.
NLW National Living Wage Higher rate of National Minimum Wage for workers aged 21 and over. Often referred to together as "NMW/NLW". Different from voluntary Real Living Wage calculated by Living Wage Foundation.
AE Auto-Enrolment (Pensions) Workplace pension scheme where employers must automatically enrol eligible workers (aged 22+ to state pension age, earning ≥£10k annually) into a qualifying pension. Minimum contributions, opt-out rights, and re-enrolment (every 3 years) required.
P45 P45 (Leaving Employment) HMRC form given to employees when they leave employment, showing pay and tax details for the year to date. New employer uses P45 to operate correct tax code. Emergency codes (e.g., 1257L W1/M1) apply without P45/P6.
Acronym Full Term Definition
DRC Domestic Reverse Charge (VAT) VAT mechanism for construction services where the customer accounts for VAT instead of the supplier. Applies to most construction services under CIS340. Designed to combat missing trader fraud in construction supply chains.
Kittel Kittel Principle EU/UK legal principle that a taxpayer who knew or should have known their transaction was connected to VAT fraud may be denied the right to deduct input VAT. Creates due diligence obligations for supply chain participants.
DR Disguised Remuneration Tax avoidance arrangements designed to pay individuals while avoiding income tax and NICs, often involving loans, offshore entities, or trusts. HMRC actively targets such schemes. Loan charge applies to outstanding loans.
Acronym Full Term Definition
SDC Supervision, Direction or Control Key factor in determining employment status under agency rules (ITEPA 2003 s44). If a worker is under supervision, direction or control by any person (client, agency, end-hirer) over how they work, PAYE must be operated. SDC alone is not the general CIS status test—apply usual status tests (control, substitution, mutuality).
MOO Mutuality of Obligation Employment status indicator examining whether the employer is obliged to provide work and the worker is obliged to accept it. Absence of MOO suggests self-employment; presence suggests employment.
SDS Status Determination Statement Document required under IR35 reforms (April 2021) where medium/large clients must provide written reasons for their determination of a contractor's employment status for tax purposes. Must be given before contract starts or worker begins work.
CEST Check Employment Status for Tax HMRC's online tool for determining whether a worker should be classified as employed or self-employed for tax purposes. Results are binding on HMRC if information provided is accurate and not relating to highly complex arrangements.
PSC Personal Service Company Limited company through which a contractor provides their services. Often used by contractors working outside IR35, but subject to IR35 rules if the underlying relationship is one of employment. Requires SDS from medium/large clients.
KID Key Information Document Plain-English factsheet (not a contract) that agencies must give to workers before they agree to an assignment (Conduct of Employment Agencies and Employment Businesses Regulations 2003). Includes worked pay illustration, deductions, who pays the worker, benefits. Must be updated within 5 working days of any change.
ITEPA 2003 Income Tax (Earnings and Pensions) Act 2003 UK tax legislation governing employment income. Section 44 contains agency rules requiring PAYE where worker is under SDC. Section 61N–61R cover off-payroll working (IR35) for public sector and (from 2021) medium/large private sector.
DBS Disclosure and Barring Service UK government service providing criminal record checks for employment purposes (particularly roles working with children or vulnerable adults). Processing DBS data requires DPA 2018 Schedule 1 condition and appropriate policy document.
Acronym Full Term Definition
Umbrella Umbrella Company Employment intermediary that employs agency workers and contractors. Handles PAYE, pension, and employment administration while the worker performs assignments for end-clients arranged through agencies. Employer NICs/apprenticeship levy must be funded from assignment rate, not charged to workers as deductions.
MUC Mini Umbrella Company Fraudulent scheme where multiple small umbrella companies are created to exploit employment allowances and avoid tax obligations. Often phoenixing after accumulating tax debt. A significant compliance risk that supply chain audits help detect.
Phoenix Phoenix Company Scheme Fraudulent practice where a company accumulates tax debts, is dissolved, and re-emerges as a new entity to escape liabilities. A key risk factor in supply chain due diligence. Tolerance of phoenix suppliers by end users enables fraud cycle.
Purported Purported Umbrella Company Entity presenting itself as a legitimate umbrella company but failing to meet compliance standards, potentially operating tax avoidance schemes or misclassifying workers.
Hybrid Hybrid Payment Model Pay arrangement combining different payment methods (e.g., PAYE + CIS, or PAYE + PSC). Requires careful status assessment to avoid disguised remuneration or employment status breaches.
Acronym Full Term Definition
UK GDPR UK General Data Protection Regulation UK data protection law (retained EU law post-Brexit) governing processing of personal data. Requires lawful basis (Art 6), data minimisation, security, transparency (Arts 13-14), and respect for data subject rights. Works alongside Data Protection Act 2018.
DPA 2018 Data Protection Act 2018 UK legislation supplementing UK GDPR. Schedule 1 sets conditions for processing special category data (health, biometric, union membership) and criminal offence data (e.g., DBS checks). Provides exemptions (crime prevention, tax collection, legal professional privilege).
DSAR Data Subject Access Request Individual's right under Art 15 UK GDPR to obtain copy of their personal data. Must respond within one month (extendable by 2 months for complex requests). Usually no fee. Must verify identity proportionately.
DPO Data Protection Officer Required role for public authorities or organisations conducting large-scale systematic monitoring or processing special category data (Art 37). Oversees data protection compliance, advises on DPIAs, and acts as contact point for ICO and data subjects.
LIA Legitimate Interests Assessment Assessment required when relying on legitimate interests (Art 6(1)(f)) as lawful basis. Three-part test: identify legitimate interest → demonstrate necessity → balancing test (interests vs individual rights). Appropriate for audit/assurance; avoid consent for audits.
DPIA Data Protection Impact Assessment Required assessment where processing is likely to result in high risk to individuals (Art 35). Must complete for large-scale, systematic monitoring or extensive special category data processing. Documents risks, mitigation measures, and necessity/proportionality.
RoPA Records of Processing Activities GDPR requirement (Art 30) documenting all personal data processing activities. Must include purposes, lawful bases, data categories, recipients, retention periods, security measures, and international transfers. Must be available to ICO on request.
IDTA International Data Transfer Agreement UK mechanism for lawfully transferring personal data outside the UK (replacing EU Standard Contractual Clauses post-Brexit). Required unless recipient country has adequacy decision or other derogation applies. Alternative: UK Addendum to EU SCCs.
SCCs Standard Contractual Clauses EU Commission-approved contract templates for international data transfers. For UK data exports, use UK Addendum to EU SCCs or UK IDTA.
Art 28 DPA Article 28 Data Processing Agreement Mandatory contract between controller and processor (Art 28 UK GDPR). Must cover: subject matter, duration, data types, processing instructions, confidentiality, security, sub-processors, data subject rights assistance, breach notification, data deletion/return, audit rights.
Art 26 Article 26 (Joint Controllers) UK GDPR provision for parties who jointly determine purposes and means of processing. Requires arrangement setting out respective responsibilities, data subject rights, and contact points. Different from controller-processor (Art 28) or controller-controller data-sharing.
Controller Data Controller Organisation that determines the purposes and means of processing personal data. Bears primary GDPR obligations. Agencies, umbrellas, and end-hirers usually act as independent controllers for their own audit/compliance purposes.
Acronym Full Term Definition
LSCA Labour Supply Chain Assurance Due diligence framework ensuring compliance with tax, employment, and ethical standards throughout the labour supply chain. Covers PAYE/CIS compliance, modern slavery, CFA 2017, worker rights, and IR35. Aims to detect exploitation, fraud, and phoenixism.
PSL Preferred Supplier List Vetted list of approved suppliers (typically umbrella companies or agencies) that meet compliance standards. Key governance control for managing supply chain risk. Should be reviewed regularly and require re-certification.
End-Hirer End-Hirer / End Client The organisation where agency or contract workers ultimately perform their work. Under current regulations, medium/large end-hirers have IR35 status determination responsibilities and supply chain due diligence obligations.
CCO Corporate Criminal Offence CFA 2017 offence: failure to prevent facilitation of tax evasion by an associated person. Three-stage liability: (1) taxpayer evades tax, (2) associated person criminally facilitates it, (3) organisation failed to prevent. Only defence: reasonable prevention procedures (RPP).
RPP Reasonable Prevention Procedures The only defence to Corporate Criminal Offence under CFA 2017. HMRC's six principles: risk assessment, proportionate procedures, top-level commitment, due diligence, communication (training), monitoring & review. Must be risk-based and documented.
SRO Senior Responsible Owner Senior person accountable for CFA 2017 compliance, risk assessments, and implementation of reasonable prevention procedures. Provides top-level commitment and board oversight.
MSAT Modern Slavery Assessment Tool UK Government tool (Home Office/Cabinet Office) for assessing modern slavery risks in supply chains. Free to organisations registered on UK Government Supplier Registration Service.
Acronym Full Term Definition
ASCA Agency Self-Certification Audit Most comprehensive audit form with 174 questions across 18 sections. Enables recruitment agencies to self-assess compliance with tax, employment, and supply chain obligations including PAYE, CIS, Modern Slavery, CFA 2017.
AUCIS Agency Umbrella CIS Audit Audit evaluating recruitment agencies' compliance with CIS requirements when engaging umbrella companies, ensuring proper tax treatment and supply chain integrity.
AUPAYE Agency Umbrella PAYE Audit Audit assessing recruitment agencies' oversight of umbrella companies' PAYE compliance, including tax deductions, National Insurance contributions, and payroll accuracy.
EHUCIS End-Hirer Umbrella CIS Audit Audit evaluating end-hirers' due diligence when engaging umbrella companies under CIS, ensuring supply chain compliance and proper contractor treatment.
EHUPAYE End-Hirer Umbrella PAYE Audit Audit assessing end-hirers' oversight of umbrella PAYE arrangements, covering payroll transparency and worker rights compliance.
EHSA End-Hirer Self-Assessment Audit Audit enabling end-hirers to self-assess their compliance with supply chain, tax, and employment obligations.
EHAA End-Hirer Assurance Audit Audit providing end-hirers with an independent assessment of their supply chain compliance, risk management, and due diligence practices.
UMBCIS Umbrella CIS Audit Audit evaluating umbrella companies' compliance with CIS requirements, including proper contractor treatment, tax deductions, and verification processes.
UMBPAYE Umbrella PAYE Audit Audit assessing umbrella companies' PAYE compliance, payroll integrity, and worker protection standards. Contains 21 sections (Section 1 info-only, Sections 2-20 audit, Section 21 declaration) vs 18 for most other audits.
Self-Cert Self-Certification Audit Generic term for labour supply chain compliance audits where organisations self-assess against tax, employment, and ethical standards. Provides documented evidence of due diligence for HMRC inspections.
Acronym Full Term Definition
Instance Audit Form Instance Individual audit submission. Users can create unlimited instances, each stored as WordPress custom post type with responses in wp_opraas_audit_responses table. Assigned to logged-in user via post_author field.
Completion Completion Score Frontend metric showing percentage of questions answered (any answer counts). Includes ALL sections: Section 1 checkbox, Section 2 (8 fields), Declaration (7 fields), and all audit questions. N/A responses count as answered.
Compliance Compliance Score Backend metric measuring quality of compliance. Scoring: Yes=5 points, No=0 points, N/A=0 points (excluded from maximum), Don't Know=1 point. EXCLUDES Sections 1, 2, and Declaration entirely. ≥80% = Compliant, 60-79% = Partially Compliant, <60% = Non-Compliant.
Evidence Evidence Files Supporting documents uploaded to substantiate audit responses. Stored in AWS S3 via WP Offload Media plugin, with Evidence Table providing S3-aware ZIP downloads that temporarily download from cloud before adding to archives.
Red Flags Red Flags Warning indicators in audit questions identifying practices that may indicate non-compliance, fraud risk (phoenixism, MUCs, disguised remuneration), or regulatory breaches requiring immediate attention and remediation.