Contractor insolvency is more common in construction than in any other industry in England and Wales. According to the Insolvency Service, 3,866 construction companies became insolvent in the 12 months to August 2026, accounting for 17% of cases where the industry was recorded.
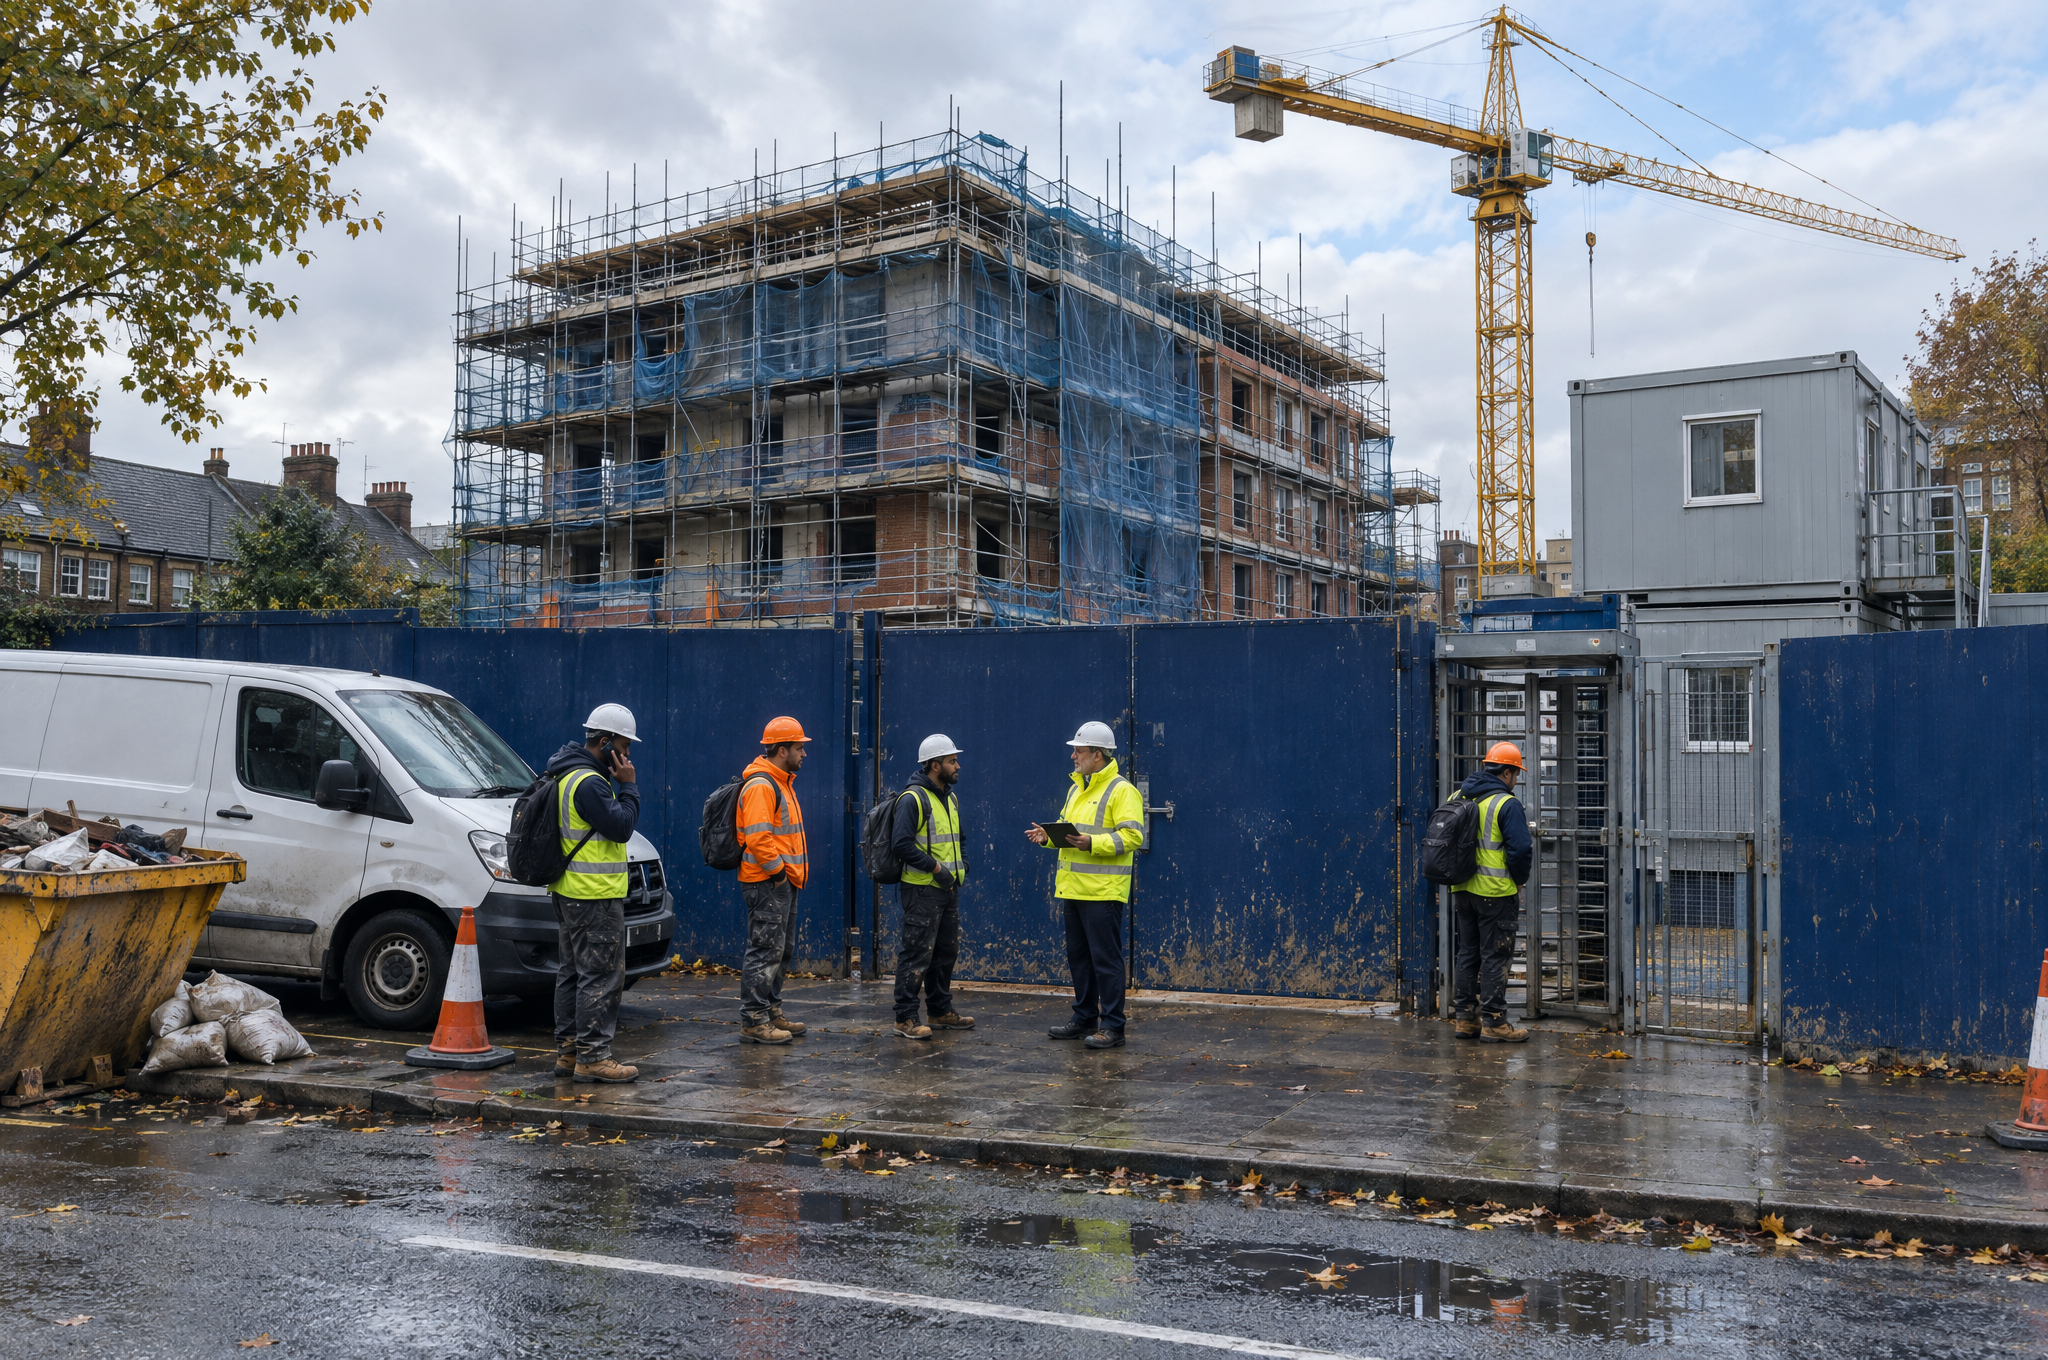
The effect is now visible on council housing sites in south-east London.
As Construction News reported on 5 October 2026, six schemes in the Royal Borough of Greenwich’s 1,750-home Greenwich Builds programme have been halted following the collapse of contractor Helix Construct. The council has secured the affected sites and is considering how work on each project can resume.
Securing a site is the immediate task.
Restarting it fairly and with confidence depends on something far less visible: knowing who was working there, which organisation supplied them, who was responsible for paying them and what assurance had already been completed.
That information sits in the labour tiers beneath the main contractor. On the day of a contractor insolvency, it can also be some of the hardest evidence to reconstruct.
What a contractor insolvency leaves behind in the labour supply chain
A main contractor rarely employs the entire workforce delivering a construction project.
Work may be delivered by directly employed staff alongside subcontractors, labour agencies, umbrella companies and self-employed workers operating under the Construction Industry Scheme (CIS).
After a contractor insolvency, those different routes matter because the consequences are not the same.
- Directly employed staff may be able to claim redundancy pay, holiday pay, unpaid wages and statutory notice pay through the government’s insolvency arrangements, subject to eligibility and statutory limits.
- Temporary workers supplied by an employment business occupy a different position. Regulation 12 of the Conduct of Employment Agencies and Employment Businesses Regulations 2003 prevents an employment business from withholding payment for work already carried out simply because the hirer has not paid it.
- Workers employed through umbrella companies introduce another organisation into the payment chain, together with separate PAYE responsibilities.
- Self-employed CIS subcontractors face a different position again. Amounts owed by an insolvent contractor may become claims against the failed business, while evidence of CIS deductions already made can become particularly important.
Each route creates different records, held by different organisations.
The council commissioning the homes may not routinely hold all of those records itself.
But when delivery stops, the questions quickly travel upstream.
Who was actually working on the project?
Who supplied them?
Who was responsible for paying them?
Were they paid for the work already completed?
And can the client still retrieve the evidence?
Why councils can lose sight of who is building their homes
Public sector buyers normally contract with the main contractor rather than every agency, subcontractor or labour supplier beneath it.
That is a normal feature of construction procurement and an important way of allocating responsibility and commercial risk.
Using several main contractors can also reduce exposure to the failure of any single supplier across a wider programme.
But diversification does not, by itself, provide visibility through the labour supply chain.
That distinction becomes important when a site has to restart after a contractor insolvency.
A replacement or completion contractor may engage some of the same trades, workers, subcontractors or labour suppliers. Without an accessible record from before the failure, establishing who previously worked on the site, how they were engaged and whether outstanding payment issues exist can become a reconstruction exercise.
There is also a wider assurance question.
HMRC’s GfC12 guidance, Help with labour supply chain assurance, encourages organisations to understand the businesses and workforce within their labour supply chains and to assure their integrity on an ongoing basis.
Among the questions HMRC asks businesses to consider are whether they have visibility through the whole supply chain, how they verify that suppliers are assuring the tiers beneath them, and who pays their workforce and how they are paid.
Those are useful questions before a contractor insolvency.
After one, they become considerably harder to answer if the evidence was never maintained.
Contractor insolvency is also a procurement governance issue
The Procurement Act 2023 provides another reason for public sector organisations to understand the financial resilience of organisations involved in delivery.
Under Schedule 7, insolvency involving a supplier or a connected person can constitute a discretionary exclusion ground.
That does not mean every subcontractor, agency or umbrella company beneath a main contractor automatically becomes a “connected person” for the purposes of the Act.
But it reinforces a broader governance principle: public buyers need sufficient visibility to understand the organisations involved in delivering their contracts and where financial distress could affect continuity, compliance or performance.
The issue is therefore larger than conventional credit control.
A supplier can pass financial checks at contract award and encounter difficulties months later.
The useful question is not simply:
Did we check the contractor?
It is:
What has changed since we checked?
Who carries the cost when contractor failure interrupts payment?
For recruitment businesses supplying temporary workers, contractor insolvency creates an immediate cash-flow problem.
Regulation 12 means an employment business cannot simply withhold a worker’s pay for work completed because the hirer has failed to pay the agency.
The employment business can therefore remain responsible for paying its workers while its own unpaid invoices become part of the insolvency process.
Where workers are employed through an umbrella company, there is now an additional tax risk to consider.
The joint and several liability provisions introduced by Finance Act 2026 inserted Chapter 11 into Part 2 of ITEPA 2003. For qualifying umbrella company payments made on or after 6 April 2026, relevant parties can be jointly and severally liable with an umbrella company for PAYE amounts that the umbrella fails to pay.
The precise liable party depends on the structure of the supply chain, but the principle is important: PAYE failure within umbrella arrangements can create financial exposure further up the chain.
That regime is distinct from older PAYE debt transfer powers.
For CIS subcontractors, the evidence question is different again.
Under the Construction Industry Scheme, contractors make deductions from payments to subcontractors and pass those deductions to HMRC. Those deductions are treated as advance payments towards the subcontractor’s tax and National Insurance liabilities.
Payment and deduction statements, together with the contractor’s CIS reporting, therefore form an important part of the evidence trail.
After a contractor insolvency, reconstructing that trail after the event can be considerably harder than maintaining it while the project is live.
Four records you need before a contractor fails
Some contractor insolvencies cannot be avoided.
Losing the labour record can.
For organisations commissioning or managing construction work, four records can make a significant difference when something goes wrong.
1. Who was on site?
Maintain a current workforce record showing the people working on each project, when they worked and their engagement route.
That should make it possible to distinguish between direct employees, agency labour, umbrella-employed workers and CIS subcontractors, and identify the organisation through which each person is engaged.
2. Who paid them?
The workforce record should connect the individual to the legal employer or paying entity.
Appropriate evidence can then be sampled against attendance or timesheet records, including payslips or CIS payment and deduction statements where relevant.
The objective is not simply to know that somebody appeared on a site.
It is to be able to follow the route between work performed, organisation responsible and payment made.
3. What has changed in the supply chain?
Financial and corporate checks should not end when the contract is awarded.
Changes at Companies House, insolvency notices, credit-risk indicators and significant changes in ownership or directors can provide signals that merit further investigation.
Not every change indicates a failing business.
The important point is that material changes prompt review rather than being discovered after the supplier has stopped trading.
4. Can you retrieve the evidence if the supplier disappears?
Contracts and governance processes should establish what labour, right-to-work, payment and supply-chain evidence can be accessed following termination or insolvency.
Otherwise, information that was readily available while a contract was live may have to be negotiated for, recovered from multiple suppliers or reconstructed after an administrator has been appointed.
A halted site can be secured quickly. Restarting it with confidence depends on knowing who was working there, through whom and how they were paid.
How OPRaaS VCD keeps the labour record current
The OPRaaS Virtual Compliance Director (OPRaaS VCD) is designed to maintain that evidence during delivery rather than reconstruct it after a problem occurs.
The platform maps the organisations supplying labour beneath each contract, including agencies, umbrella companies and CIS subcontractors, and records the paying entity associated with each worker.
Right-to-work and identity evidence can be captured through the onboarding and assurance process, while pay evidence and CIS documentation can be sampled against timesheets and workforce records. Where an assurance gap is identified, responsibility for resolving it can be assigned and tracked.
Supplier assurance can also continue throughout the engagement, including monitoring Companies House for director and ownership changes and Creditsafe for credit-risk signals.
If a contractor or labour supplier subsequently fails, the objective is that the workforce record, supplier history and assurance evidence already exist.
The question changes from:
“Can we reconstruct what was happening on this site?”
to:
“Can we produce the evidence?”
That same principle is addressed in Module 3 of the OPRaaS LSCA Self-Certification Course through its Contingent Workforce Tracking topic.
One practical test is simple:
Could your organisation produce a compliant headcount report for its contingent workforce within 24 hours?
For a construction programme, it becomes simpler still:
Can you show who was on this site, who engaged them and who paid them?
OPRaaS is approved on the UK Government Commercial Agency (formerly Crown Commercial Service) frameworks including RM6310 Audit & Assurance Services (Lots 2 & 4), RM6219 Learning & Training Services DPS, RM6237 Learning & Training Services DPS and G-Cloud 15.
What boards and commissioners should test before the next contractor insolvency
Board directors, council commissioners, procurement leaders, main contractors, recruitment agencies and MSPs do not need to wait for an insolvency to discover whether the evidence exists.
Pick one live site.
Ask for a list of the people who worked there last week.
For each person, ask:
- who engaged them;
- which organisation pays them;
- whether they are direct, agency, umbrella or CIS;
- what right-to-work and identity assurance is held; and
- what evidence demonstrates that the work recorded and payment made can be reconciled.
Then ask how quickly that information could still be produced if the main contractor stopped trading tomorrow.
If the list takes more than a day to assemble, the gap already exists.
Some contractor failures cannot be avoided.
Losing sight of the labour supply chain when one happens can.
Compliance is your asset. Evidenced daily.
Read next
“Why supplier insolvency is still a live risk across the construction labour supply chain.“
This article draws on the Construction News report published on 5 October 2026, Insolvency Service company insolvency statistics for August 2026, GOV.UK guidance on employer insolvency, the Conduct of Employment Agencies and Employment Businesses Regulations 2003, the Procurement Act 2023, Finance Act 2026, HMRC Construction Industry Scheme guidance and HMRC’s GfC12 Help with labour supply chain assurance.
Talk to OPRaaS about your labour supply chain.
Use the contact form alongside this article or email info@opraas.co.uk.
This article is editorial commentary by OPRaaS Limited (On-Pay-Roll-as-a-Service), drawing on published research, legislation and government guidance. It provides general information and does not constitute legal, tax, employment or compliance advice. Obligations vary according to organisation, contractual arrangements and individual engagements. Appropriate professional advice should be obtained before acting on a specific position.